- Demand for small office space in central Malta has risen sharply over the past month. The brief is remarkably consistent: roughly 80 to 200 sqm, inside a managed business centre, with reserved parking, in Attard, Naxxar, Mriehel, Birkirkara or San Gwann.
- Supply does not line up. Malta's business centres cluster in Sliema, St Julian's, Gzira, Msida and the Mriehel CBD, and most sit on floor plates above 500 sqm. Units at 80–200 sqm do exist, but they depend on subdivision or a managed configuration.
- As a result, tenants are compromising on one of three things: locality, business centre format, or unit size. Meanwhile the pricing gap is wide. Central belt asking rents run roughly €120–€220 per sqm per year, against €260–€350+ in Sliema.
By Emmanuel DeGiovanni, Senior Office Agent and Founder, OfficeSpace.Rent · Published 5 October 2026
Finding small office space in central Malta has become unexpectedly difficult. Over the past month, a clear pattern has run through our enquiries. Businesses want 80 to 200 sqm — broadly 8 to 20 desks — in the inland central belt rather than the coastal districts. Moreover, they want it inside a proper business centre, with managed common areas and a reception presence. They also want reserved parking. Each requirement sounds modest on its own. Together, however, they describe something Malta's office market currently supplies very thinly.
Table of Contents
- Small office space in central Malta: what we are seeing
- The requirement profile
- Why demand for small office space in central Malta is rising
- Where Malta's business centres actually are
- The floor plate mismatch
- What tenants searching for small office space in central Malta do
- The pricing trade-off
- What this means for landlords
- How to run a small office search in central Malta
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| The demand | 80–200 sqm in Attard, Naxxar, Mriehel, Birkirkara and San Gwann. Business centre format and reserved parking are both treated as non-negotiable. |
| The supply | Business centres cluster on the coast and in Mriehel. Inland stock is mostly converted townhouses, maisonettes and standalone blocks. |
| The size problem | Underlying floor plates are large. Therefore units at this size depend on subdivision or a managed configuration. |
| The pricing gap | Central belt asking rents run roughly €120–€220 per sqm per year. Sliema runs €260–€350+, and St Julian's €280–€380+. |
| The practical answer | Five routes are in use. Negotiated subdivision and managed suites are the two most productive. |
Small office space in central Malta: what we are seeing
Through September 2026, one requirement profile kept repeating in our enquiry flow. Tenants asked for roughly 80 to 200 sqm. They named Attard, Naxxar, Mriehel, Birkirkara or San Gwann. Furthermore, they specified business centre accommodation rather than a converted or standalone building. Finally, they treated reserved parking as a requirement, not a preference.
What makes this worth writing up is not volume. Rather, it is consistency. These enquiries arrive independently of one another, yet they describe very nearly the same brief.
Three things should be clear about what this is. First, it is a qualitative observation rather than a measured statistic. In other words, we are describing a pattern, not publishing an index. Second, it reflects enquiry activity rather than transactions. Some of these requirements will resolve elsewhere, and some will not resolve at all. Third, it reflects our own enquiry flow. We are a specialist office agency with a particular client profile, not a census of the Maltese market.
Where this article cites rental ranges, those are asking rents drawn from our own listings, exclusive of VAT and service charges. Our definitions and limitations appear in full in our market data methodology.
The requirement profile
The brief barely varies between enquiries. Consequently it is easy to set out.
| Requirement | What tenants ask for, and why |
|---|---|
| 80–200 sqm | Roughly 8 to 20 desks. Large enough to need a real office, yet small enough that a 500 sqm floor is unusable. |
| Central inland locality | Attard, Naxxar, Mriehel, Birkirkara, San Gwann. Chosen to equalise commutes, not for address prestige. |
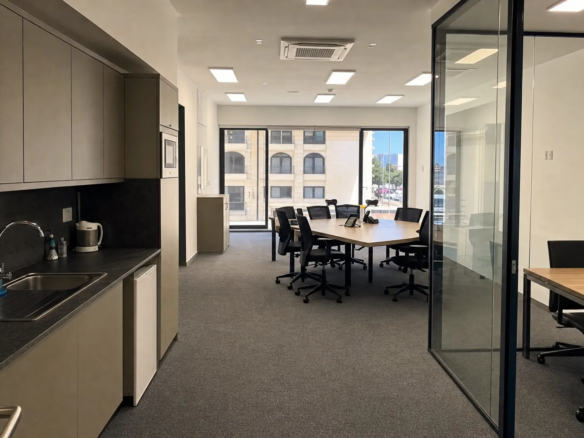
| Business centre format | Managed common areas, lift access, a reception presence and other commercial tenants. Tenants explicitly rule out converted townhouses. |
| Reserved parking | Allocated spaces, not "parking nearby". This single requirement eliminates more options than any other. |
| Ready or near-ready | Few tenants at this size want to carry a full fit-out of €300–€500 per sqm on a 150 sqm unit. |
| Class 4A in place | Increasingly asked about directly. See our guide to the Class 4A office permit in Malta. |
The telling detail: these tenants are not asking for a cheaper version of a Sliema office. Instead, they want something structurally different — a managed building, centrally located, at a size the managed-building market has historically not supplied.
Why demand for small office space in central Malta is rising
No single factor explains the shift. However, five come up repeatedly.
Commute has become a retention issue
Malta's labour market is demonstrably tight. The NSO recorded 9,619 vacancies and a 3.1% job vacancy rate in Q2 2026, rising to 5.3% among small enterprises (NSO Malta). Against that backdrop, employers tell us commute time now surfaces regularly in recruitment conversations. A central inland location does not minimise anyone's journey. Rather, it equalises them, which for a distributed team is often the better outcome.
Parking has become a deal-breaker
In the harbour districts, parking is scarce and expensive. For a 15-person team, that friction compounds daily. By contrast, reserved spaces inland are genuinely achievable. Consequently, tenants have started treating parking as a primary filter rather than a bonus.
Footprints have settled smaller
Hybrid working has reduced the permanent desk requirement for many occupiers. As a result, some now operate from materially smaller footprints than they would have taken five years ago. Rather than renewing on an oversized floor, they use lease expiry to right-size.
Businesses are graduating out of serviced offices
A company that started in a serviced office in Malta and grown to 12 or 15 staff usually wants its own identity and its own lease. Yet it does not want a full floor. That transition point lands squarely in the gap.
Cost discipline
Central belt asking rents sit materially below the harbour districts — in some cases by around 40 to 50%. Over a five-year term, the saving on 150 sqm is substantial. Increasingly, therefore, it is finance rather than operations starting the conversation. Our guide to assessing office rental costs in Malta covers how to model this properly.
Where Malta's business centres actually are
Malta's purpose-built business centre stock grew where commercial demand historically concentrated. That meant the harbour coast and, more recently, the Mriehel Central Business District. The central inland localities developed differently. Their commercial stock is overwhelmingly converted: townhouses and private dwellings adapted to office use, standalone blocks and upper floors above retail.
That history still shapes these markets. Naxxar, despite healthy listing volume, is not a serviced office hub and has no commercial tower district. Its office market is dominated by private, traditional space, much of it in converted townhouses suiting law firms, notaries and architects. Attard reads similarly: duplexes, penthouses and townhouse conversions. These are often excellent spaces. They are simply not business centres.
| Locality | Dominant office stock | Business centre options at 80–200 sqm |
|---|---|---|
| Attard | Townhouse and villa conversions, duplexes, penthouse offices | Very limited |
| Naxxar | Private traditional offices and conversions; some industrial estate stock | Very limited — not a serviced office or tower district |
| San Gwann | Mixed: genuine business centres alongside converted stock | Some. Conventional units are often 490 sqm upward, though managed operators such as The Hub offer suites in this bracket, including an 80 sqm annex |
| Birkirkara | Mixed, with genuine Class-A stock at the bypass and Swatar edge | Limited conventional; better served by managed suites |
| Mriehel CBD | Purpose-built Grade A and Class-A towers and campuses | Business centres plentiful, but configured for large plates |
For a wider view of how these districts compare, see our guide to Malta office locations.
The floor plate mismatch
Suppose a tenant accepts relocating to where the business centres are. A second problem then appears. Malta's business centre stock was built around larger occupiers, so the defining buildings carry floor plates a 15-person company cannot absorb whole.
| Building | District | Floor plate | Smallest unit / divisibility |
|---|---|---|---|
| Wembley Business Centre | Gzira | Up to ~1,800 sqm | From ~390 sqm |
| Marina Business Centre | Ta' Xbiex | ~800 sqm site footprint; ~3,532 sqm NLA over six floors | Floors subdividable — confirm at enquiry |
| Tagliaferro Business Centre | Sliema | ~800 sqm | From ~70 sqm — six modules per floor |
| Savoy Business Centre | Sliema | ~750 sqm — completion targeted end-2027 | Not yet let; configuration to be confirmed |
| OPUS Business Centre | St Julian's | ~572 sqm | Subdivided units available |
| Portomaso Business Tower | St Julian's | ~295 sqm upper, ~465 sqm lower | Floors can be subdivided |
| ST Tower Business Centre | Ta' Xbiex | ~360–365 sqm gross per level (incl. ~65 sqm terrace) | Floors can be divided |
The important nuance is this. Large underlying plates do not automatically mean small units are unavailable. Tagliaferro was designed to be subdivided and lets from around 70 sqm upward. ST Tower's floors can be divided too, and several other buildings will partition on request.
Therefore the real constraint is not that 80–200 sqm units cannot exist in Malta's business centres. Instead, they depend on a landlord willing to subdivide, or on a managed-office configuration. Crucially, both are concentrated in the coastal districts rather than the inland localities this demand is asking for. A tenant wanting 120 sqm in a business centre in Attard must therefore secure a subdivision, accept a managed product, accept Mriehel, or leave the business centre category.
Where the demand is, and where the supply is
The diagram below sets the two against each other.
What tenants searching for small office space in central Malta do
In our recent searches, tenants in this bracket have frequently compromised on at least one part of the brief. Five resolutions keep appearing, in rough order of frequency.
| Route | What it involves, and the trade-off |
|---|---|
| 1. Negotiated subdivision | Persuading a landlord to split a larger plate. This is often achievable where a floor has sat vacant, and it is the most productive route in this bracket. However, expect to trade a longer term for it. |
| 2. Managed suite inland | Ewropa in Birkirkara and Avenue77 in Mriehel both run managed suites alongside conventional floors. The Hub in San Gwann operates around 40 flexible offices, including an 80 sqm annex sized for roughly eight workstations. The trade-off is an all-inclusive price and less control over identity. |
| 3. Accept Mriehel CBD | For tenants targeting Attard or Birkirkara, Mriehel is usually a modest geographic compromise. Moreover it brings genuine Class-A stock and real parking. |
| 4. Drop the business centre requirement | Taking a well-finished standalone or converted building in the target locality. This opens the market substantially and often improves the rent. In exchange, you lose managed common areas and a shared reception. |
| 5. Shift to Msida or Gzira | Both are more central than Sliema, with genuine business centre stock and rents below the prime coastal districts. Browse offices in Msida and offices in Gzira. |
Pro Tip: decide early which of your three requirements you are least attached to — locality, business centre format, or unit size. In our experience, tenants who identify their flexible variable at the outset reach a workable shortlist faster.
The pricing trade-off
The cost gap between the central belt and the harbour districts is wide enough to model properly. The ranges below are indicative asking rents observed across OfficeSpace.Rent inventory, exclusive of VAT and service charges. They are not market-wide achieved-rent statistics. Grade, finish and building type move them considerably within each district.
| District | Asking range (€/sqm/yr) | Indicative annual rent on 150 sqm |
|---|---|---|
| Attard | €120 – €200 | €18,000 – €30,000 |
| San Gwann | €130 – €200 | €19,500 – €30,000 |
| Naxxar | €130 – €220 | €19,500 – €33,000 |
| Mriehel CBD | €155 – €350 | €23,250 – €52,500 |
| Sliema | €260 – €350+ | €39,000 – €52,500+ |
| St Julian's | €280 – €380+ | €42,000 – €57,000+ |
At the extremes of these ranges, the difference is striking. An Attard office at €120 against a St Julian's office at €380 produces roughly €39,000 a year before VAT on 150 sqm. Over five years, that is around €195,000 before any rent escalation. Most real comparisons will be narrower. Even so, the mid-range gap deserves modelling rather than instinct.
Remember too that headline rent is not the whole cost. Service charges, parking, utilities and fit-out obligations all belong in the comparison. For district-by-district context, see our Malta office market guide.
What this means for landlords and developers
If you own inland commercial property, this demand pattern is worth reading carefully.
Subdivision is currently under-supplied. Landlords willing to partition larger inland plates into 80–200 sqm units with allocated parking are meeting a requirement the market is not otherwise serving. In our experience, they also let faster, to tenants prepared to commit to longer terms.
Parking allocation outweighs specification. Among these enquiries, reserved parking eliminates more otherwise-suitable options than finish quality, age or amenity. Consequently, an inland building with allocated spaces competes well above its specification grade.
The gap between converted and managed is commercially meaningful. Tenants reject good converted stock because it lacks lift access, maintained common areas and a reception presence. For some owners, therefore, closing that gap is a modest investment rather than a redevelopment.
How to run a small office search in central Malta
Three things make a material difference in this bracket.
Start earlier than the size suggests. Tenants assume a 150 sqm requirement moves quickly because it is small. In this segment, however, the opposite applies. You are waiting for a specific configuration rather than choosing among many. Therefore allow four to six months.
Ask about subdivision explicitly. A 500 sqm floor advertised whole is not necessarily only available whole. Whether a landlord will split has to be asked building by building, because the answer never appears in the listing.
Rank your three variables before you start. Locality, business centre format, unit size — know which one gives first.
OfficeSpace.Rent has specialised exclusively in Maltese commercial office space since 2016. We track more than 3,800 listings across every district, including space not yet publicly marketed and landlords open to subdivision. If you are weighing a requirement in this bracket, contact our team with your headcount, target localities, parking requirement and lease expiry date.
Alternatively, browse current availability directly: Attard, Naxxar, San Gwann, Birkirkara, Mriehel CBD, or search all offices in Malta.
We are a commercial agency and earn fees from letting and selling office space. We publish that here for the same reason we publish it in our methodology: a reader should be able to weigh what we report with our position in view.
Frequently asked questions
Is there small office space in central Malta inside business centres?
Yes, but it is scarce and unevenly spread. San Gwann has genuine business centre buildings, and The Hub operates around 40 flexible offices there, including an 80 sqm annex sized for roughly eight workstations. Conventional units in the same locality, however, are frequently 490 sqm and upward. Naxxar is not a serviced office or tower district, and Attard's stock is similarly conversion-led. Tenants needing business centre format at 80–200 sqm in these localities usually resolve it through a managed suite, negotiated subdivision, or by accepting Mriehel CBD.
Why are there so few small offices in Malta's business centres?
Malta's business centre stock was developed around larger occupiers and designed with floor plates to match. These typically run from around 295 sqm to 800 sqm and beyond. Smaller units do exist where a building was designed for them. Tagliaferro in Sliema, for instance, lets from around 70 sqm across six modules per floor, and several other buildings will divide floors on request. Outside purpose-designed buildings, though, subdivision creates partition cost and more complex letting, so it has historically happened only where a floor proved hard to let whole.
Is small office space in central Malta cheaper than Sliema or St Julian's?
Substantially, in many cases. Indicative asking rents in the central belt run between €120 and €220 per sqm per year. By comparison, Sliema runs €260 to €350+, and St Julian's €280 to €380+. At the extremes, the difference on 150 sqm reaches roughly €39,000 a year before VAT, or around €195,000 over five years before escalation. Most real comparisons are narrower. These are asking rents exclusive of VAT and service charges, not achieved-rent statistics.
Can I rent part of a floor in a Malta business centre?
Often, yes — but it is rarely advertised. A floor marketed whole is not necessarily only available whole. Landlords holding space that has been vacant for a period are increasingly willing to partition. Typically this involves agreeing who carries the partition cost and accepting a longer lease term in exchange. In our experience, this is the most productive route for tenants in the 80–200 sqm bracket.
How important is reserved parking when renting an office in Malta?
In the current market it is one of the most decisive factors. Among enquiries in this bracket, parking eliminates more otherwise-suitable options than finish quality or building age. Parking in the harbour districts is scarce and expensive, which drives much of the shift toward central inland localities. Importantly, tenants should distinguish between allocated spaces included in the lease and general availability nearby. Marketing material frequently conflates the two.
Recommended reading
- Offices in Mriehel CBD
- Offices in Birkirkara
- Offices in San Gwann
- Offices in Naxxar
- Serviced Offices in Malta
- Malta Office Market Guide
- Malta Office Locations: A Comprehensive Guide
- How to Assess Office Rental Costs in Malta
- Office Lease Negotiation Malta: Essential Tips
- Class 4A Office Permit Malta
- Market Data Methodology